Skrill - Fast, secure payments

Screenshots
Details
- Rating
- 3.97K reviews
- Version
- 3.191.0-2026081013
- Developer
- Paysafe Holdings UK Limited
Analysis by Norviv
When I need a practical way to move money from my phone, I look for three things first: a clear interface, a trustworthy company behind it, and enough flexibility to fit real-life payments rather than just one narrow task. Skrill makes a strong case on those basics. It is a free finance app from Paysafe Holdings UK Limited, built around sending and managing money from a mobile device. My overall view is positive, but with an important qualification: it is most useful for people who regularly need a digital wallet for transfers and online payments, not for someone who only wants a simple everyday banking replacement.
The app has been available since 2014, which gives it more maturity than many newer payment wallets. Its current version is 3.191.0-2026081013 and it works on Android 8.0 or later. On the store, it has a 4.5 average from around 239 thousand ratings, with over 10 million installs. Those figures do not replace personal judgment, but they do suggest that Skrill is an established service rather than an experimental app that might disappear after a few months.
What using Skrill feels like in everyday situations
The central experience is straightforward: I open the app, sign in, and use the wallet as a place to organize money transfers and payments. The store summary focuses on transferring money with a phone, and that is the right way to understand it. Skrill is not trying to be a full financial institution inside my pocket. Its value comes from making selected money movements easier to handle digitally.
For example, imagine I need to send money to someone while I am away from my computer. A traditional route might involve opening a bank website, searching through several menus, checking recipient details, and then confirming a transfer through a separate security step. With Skrill, the appeal is having a mobile-first route that keeps the payment activity in one app. I still need to check every recipient and amount carefully, but the process feels designed for quick phone use rather than adapted from a desktop banking portal.
That distinction matters when I am paying online or moving money between people. A bank account is usually the better foundation for salary payments, direct debits, and long-term financial management. Skrill is more like a focused wallet layer. It can be convenient when I want separation between a particular online payment activity and my main bank account, or when a recipient expects a digital payment rather than a conventional bank transfer.
The interface is also easier to approach than the language used by many financial services. I do not have to think of it as a complicated investment product or a budgeting system. I think of it as a digital place for sending money and handling payments. That narrow purpose helps the app feel less intimidating for someone who is comfortable using a smartphone but does not want to navigate a dense banking application.
The strongest reason to choose it
For me, Skrill’s biggest strength is convenience across situations where a phone is the most practical tool available. I can be traveling, shopping online, or settling a personal expense and still have a payment app designed around mobile access. The benefit is not that it magically removes every step from a financial transaction. The benefit is that the steps are gathered into a familiar wallet experience.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Another advantage is the balance between accessibility and a serious financial purpose. The app is free to download, and its content rating is Everyone, so it is presented as a broadly accessible finance tool rather than a specialist product. That does not mean every financial action is free or suitable for every user; I would always inspect the details shown before confirming a transaction. Still, the starting point is approachable for ordinary users.
I also appreciate that the app can make a useful boundary between spending and banking. Some people prefer not to expose their primary bank details every time they make an online payment. A wallet can provide an additional layer of organization, letting them keep a particular balance or payment activity separate. That separation is not automatically safer in every circumstance, but it can be valuable for people who want clearer control over where they keep money intended for digital purchases.
A less obvious benefit is the ability to create a repeatable payment routine. If I use the same wallet for a certain type of transfer, I can build a habit of checking the balance, recipient, and final amount in one place before confirming. That sounds minor, but consistent routines reduce careless mistakes. I would not rely on memory or a familiar recipient name alone; I would still verify the destination every time, especially when transferring a meaningful amount.
Where the experience needs more care
The main weakness is that a mobile wallet can feel simple at the beginning while still requiring careful attention to transaction details. Users may assume that “free” means every possible action has no cost, but that is not a safe assumption for any financial app. Before sending money, I would review the displayed terms, currency, recipient information, and final amount rather than tapping through quickly.
There is also a trade-off between convenience and dependence on the service’s ecosystem. If the person I want to pay uses a different method, Skrill may not be the most direct option. A bank transfer could be more suitable for a formal payment, while another payment service may be better when a whole group already uses it. The best wallet is often determined by the people and merchants on the other side, not just by the quality of the app itself.
I would also avoid treating Skrill as a replacement for a complete bank account. Someone who wants detailed budgeting, savings goals, account aggregation, loan management, or a broad view of household finances may find a conventional banking app more appropriate. Skrill’s focused design is a strength for payments, but it is also the reason I would not choose it as my only financial tool.
Another practical limitation is the need to stay alert when using a phone in public. A payment app is convenient on the move, but convenience can encourage rushed decisions. I would not send money while distracted, on an unsecured shared device, or with someone looking over my shoulder. I would use a strong device lock, keep the app updated, and pause if a payment request seems unusual. These are sensible habits for any finance app, but they matter especially when the entire transaction can happen in a few taps.
Useful habits that make the app safer and clearer
My first tip is to treat the confirmation screen as a checkpoint, not a formality. Before approving a transfer, I would read the recipient details, amount, currency, and any visible charge. This catches errors that a quick glance at a familiar name can miss. It is particularly useful when a contact has more than one account or when an online payment involves conversion between currencies.
My second tip is to keep the wallet’s purpose narrow. If I use it for online purchases, I would avoid mixing that activity with money intended for rent or essential bills. Separating purposes makes the balance easier to understand and limits the damage if I make an avoidable payment mistake. This is not a special feature claim; it is a workflow choice that makes a digital wallet more manageable.
My third tip is to check the app after an important transaction rather than assuming the action completed exactly as intended. I would look for the updated status and keep any useful confirmation information until the recipient has received the money. That habit helps distinguish a completed payment from a pending or interrupted attempt, and it gives me a clearer record when I need to investigate a problem.
A fourth useful approach is to compare the final cost before choosing Skrill for a particular transfer. The most convenient route is not always the least expensive once currency conversion or other transaction conditions are considered. If I am sending a small amount, a fixed charge can matter more than it would for a larger payment. If I am paying internationally, I would compare the complete amount shown by Skrill with the amount offered by my bank or another established payment service.
Who will get the most from it
I think Skrill is a good fit for people who want a dedicated mobile wallet for online payments and person-to-person money movement. It is especially appealing to users who value having a separate payment balance, prefer phone-based access, or regularly deal with digital transactions that are awkward through a standard bank interface.
It can also suit someone who is beginning to use digital finance and wants a focused app instead of a large banking dashboard filled with unrelated tools. The Everyone content rating and free availability make the entry point approachable, although financial responsibility still matters more than the simplicity of the download. I would explain the payment flow to a less experienced user and encourage them to start with small, familiar transactions until they understand how the wallet works.
On the other hand, I would steer away from it if my main goal were household budgeting or complete banking management. A person who wants one app for savings, bills, loans, investments, and detailed spending analysis should look at a full-service bank or money-management application. I would also choose a different option when the recipient, merchant, or employer already requires a specific payment rail. No wallet is useful if it does not fit the actual transaction.
How it compares with familiar alternatives
Compared with a bank’s mobile app, Skrill feels more focused on the payment wallet itself. A bank app usually wins for account history, standing payments, and direct control of a traditional current account. Skrill can be more convenient for a distinct online payment workflow, but I would not expect it to replace all the services offered by my bank.
Compared with general peer-to-peer payment apps, Skrill’s appeal depends more on whether its payment environment matches my needs. A local peer-to-peer service may be faster for splitting a restaurant bill when everyone in the group already uses it. Skrill becomes more attractive when I want a dedicated wallet for online activity or a payment route that is separate from my everyday banking habits.
Compared with cash, the app offers better digital traceability and remote convenience, but cash does not depend on a phone, login, battery, or service availability. Compared with a card used directly online, a wallet can provide an additional layer of organization, though it also introduces another account to monitor. I see Skrill as a useful middle ground, not a universal winner in every payment situation.
My final recommendation
After using it as a mobile finance tool, I see Skrill as a sensible choice for people who want convenient transfers and a dedicated digital wallet rather than a complete replacement for their bank. Its long availability, broad adoption, free entry point, and clear payment focus give it a solid foundation. The app is at its best when I already know why I need a wallet and want that task handled from my phone.
The important caution is to slow down at the moments that matter. I would check the complete transaction cost, confirm the recipient, keep the app and device protected, and compare alternatives when the payment is international or unusually important. Those habits do not make the experience difficult; they prevent the convenience from turning into carelessness.
My verdict is positive for mobile-first payments, with realistic limits. I would recommend Skrill to a friend who needs a focused way to transfer money and manage online payments, especially if the people or services involved already support it. I would not recommend making it the only financial app in a person’s life. Used for the job it is designed to do, it is approachable, established, and genuinely useful; used as a substitute for full banking, it is likely to feel too narrow.
Frequently Asked Questions
01What is Skrill and what can I use it for?
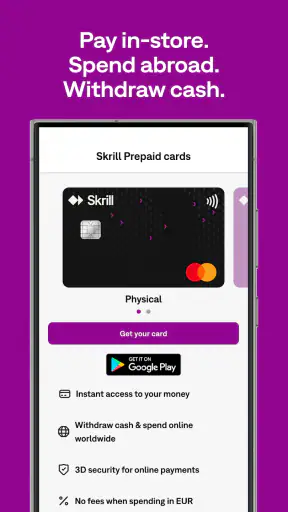
Skrill is a digital wallet and online payment service that lets you send and receive money, pay merchants, and manage funds from a mobile device or web browser. Depending on your country, it may also support international transfers, prepaid card services, cryptocurrency features, and other financial tools. Available features, currencies, and transaction limits can vary by region.
02Is Skrill safe to use for online payments?
Skrill uses account security measures such as password protection, identity verification, transaction monitoring, and additional login or payment checks where available. However, users still need to protect their credentials, avoid suspicious links, and enable available security options. Skrill is not a bank in every market, so account protection, withdrawal rules, and regulatory coverage may differ depending on your location.
03Are there fees for using Skrill?
Skrill may charge fees for certain activities, including sending money, currency conversion, withdrawing funds, receiving payments, or leaving an account inactive for a period of time. The exact cost depends on the transaction type, payment method, currency, and country. Before confirming a transaction, review the displayed fee and exchange rate carefully, as the final amount may differ from the amount sent.
04What documents are required to verify a Skrill account?
Skrill may ask users to verify their identity before allowing higher limits or certain financial operations. Verification can involve a government-issued identification document, proof of address, and sometimes additional information about the source or purpose of funds. Make sure submitted documents are valid, readable, and match your account details. Requirements can change according to local regulations and account activity.
05Can I withdraw money from Skrill to my bank account or card?
In many supported countries, Skrill allows users to withdraw funds to an eligible bank account or payment card, although availability depends on location, currency, and account status. Processing times and fees can vary, and some cards or banks may not be supported. Check the withdrawal section in the app before transferring money, and confirm that your account information is accurate to avoid delays.


